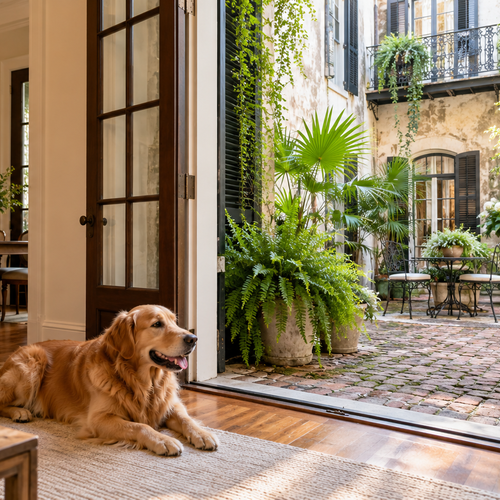
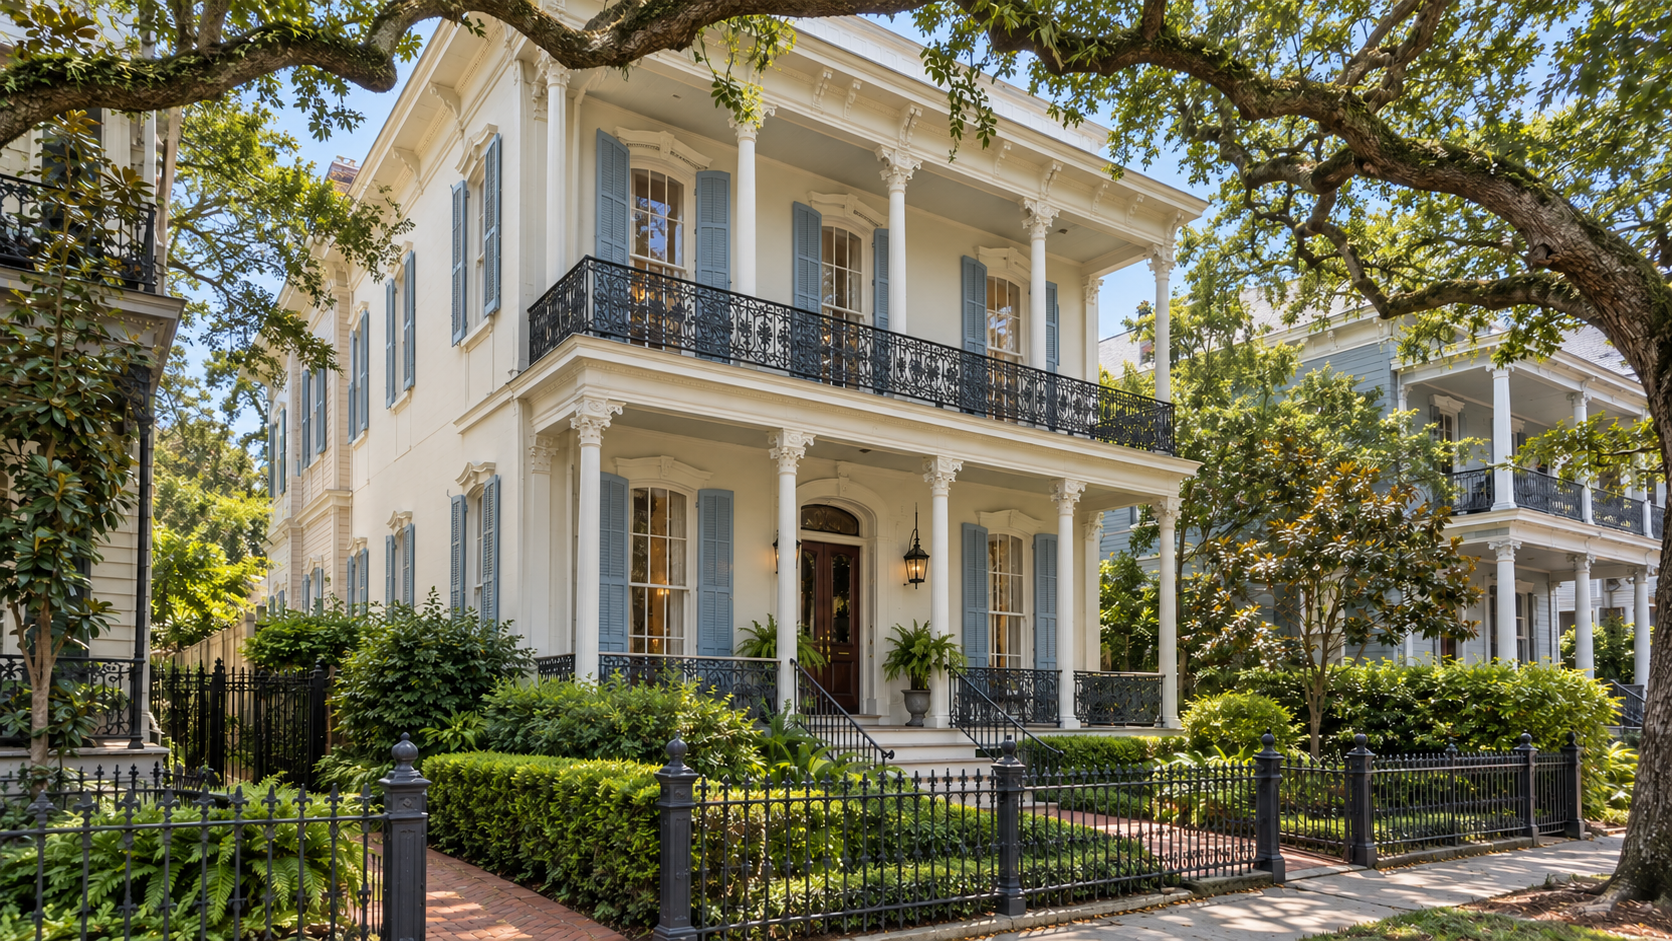
A French Quarter condo with a private courtyard. A Warehouse District residence with secure parking. An Uptown home with the architectural character you have always wanted. For buyers with cash available, today’s New Orleans real estate market offers a compelling opportunity to pursue the right property with greater flexibility.
Cash buyers can avoid mortgage interest, offer sellers a simpler path to closing, and consider properties that may be more complicated to finance. When those advantages meet a well-priced home and a seller ready to move forward, the result can be a strong purchase.
Now can be an excellent time to be a cash buyer in New Orleans—especially when you combine financial readiness with careful property selection.
Why Today’s New Orleans Market Creates an Opening
According to Redfin, over the three months ending August 2026, New Orleans homes sold for a median price of approximately $340,000, down 1.5% from the same period a year earlier. Homes averaged around 65 days on the market, and multiple offers were described as rare. Redfin
For buyers, those conditions can create room to compare properties, review ownership costs, and negotiate terms.
The opportunity still depends on the property. Citywide figures cover different neighborhoods, price points, and property types. A well-priced, renovated home or a desirable condo can attract attention quickly. Your offer should reflect recent comparable sales and the property’s condition, rather than an assumed discount.
Mortgage Rates Give Cash Buyers a Clear Advantage
Freddie Mac reported an average 30-year fixed mortgage rate of 7.03% on September 24, 2026. That national benchmark helps explain why borrowing costs remain a significant part of a financed buyer’s budget. Freddie Mac
A cash buyer can evaluate the purchase without a mortgage payment or the need to qualify for a loan.
Consider an illustrative $400,000 purchase. A buyer putting 20% down would borrow $320,000. At a hypothetical 7% fixed interest rate over 30 years, the monthly principal-and-interest payment would be approximately $2,129, before taxes, insurance, and association dues.
A buyer paying entirely with cash avoids that mortgage payment. The tradeoff is committing an additional $320,000 to the property, which should be weighed against reserves and other uses for the money.
For buyers who can comfortably make that commitment, owning without mortgage debt can provide more control over monthly expenses.
Sellers May Value the Certainty of Your Offer
Price matters, but sellers also want confidence that a transaction will close.
A cash offer can remove mortgage underwriting and lender approval from the process. That may be especially useful to a seller coordinating another purchase, relocating, settling an estate, or carrying expenses on a vacant property.
A well-prepared cash buyer may be able to negotiate:
- A lower purchase price supported by comparable sales.
- Seller-paid closing expenses.
- Repairs or an agreed adjustment for needed work.
- A closing date that fits both parties.
- Included appliances or other agreed items.
Cash does not guarantee that a seller will accept a lower offer. A higher financed offer with strong terms may still be more attractive. Your advantage comes from presenting a credible package: documented funds, realistic deadlines, and clear contract terms.
Our guide to cash offers versus financing in New Orleans explains how sellers evaluate those differences.
Cash Can Expand Your New Orleans Condo Options
For condo buyers, cash can provide flexibility beyond the individual unit.
Mortgage approval can depend on the condominium project as well as the borrower. Association finances, insurance, building condition, litigation, and other factors can affect financing eligibility.
A cash buyer does not need a lender to approve the project for the immediate purchase. That can expand the range of condos worth considering, including some properties with limited conventional financing options.
The next step is understanding why financing is difficult. A building’s financial or physical problems still affect a cash owner. Limited financing options may also affect future resale or your ability to borrow against the property later.
Before buying, read our explanation of warrantable and non-warrantable New Orleans condos and our guide to evaluating condo associations.
A desirable unit becomes a stronger opportunity when the building’s finances, maintenance plans, and ownership costs also make sense.
Longer-Listed Properties Deserve a Closer Look
A property that has been available for several months may offer a productive starting point for negotiation.
Sometimes the original asking price was too ambitious. Sometimes the home needs cosmetic updates, has limited showing availability, or appeals to a narrower group of buyers. Other properties have more substantial issues that require investigation.
Cash buyers can look for homes with price reductions, listings that returned to the market, or properties where a straightforward closing would be valuable to the seller.
The goal is to identify a sound property whose price can be brought into line with its condition and comparable sales. A large reduction from an inflated asking price is less meaningful than a purchase that represents fair value.
Our article on why some New Orleans homes are sitting on the market longer explains what buyers should investigate.
Keep Enough Cash for Ownership After Closing
Buying without a mortgage simplifies part of the transaction, but you still need a complete ownership budget.
Before making an offer, account for:
- Property taxes and current insurance quotes.
- Flood exposure and appropriate coverage.
- Roof, foundation, plumbing, electrical, and HVAC condition.
- Closing expenses and immediate repairs.
- Condo dues, reserves, and potential special assessments.
- Emergency savings and ongoing maintenance.
Get insurance estimates during your evaluation, even when a lender is not requiring coverage. Our guide to insurance-ready homes in New Orleans explains how property condition and documentation can help buyers assess this part of ownership.
Your cash advantage is strongest when you can purchase comfortably and retain the resources to care for the property.
FAQs About Buying With Cash in New Orleans
Can a cash buyer get a better price?
Sometimes. A seller may accept a lower price in exchange for fewer financing uncertainties or a convenient closing date. The result depends on comparable sales, competing offers, property condition, and the seller’s priorities. There is no standard cash-buyer discount.
Should a cash buyer still get a home inspection?
Yes. Paying cash does not reveal hidden defects. An inspection and any recommended specialist evaluations help you understand the property before committing to ownership. Negotiate enough time to complete that review.
Do cash buyers need an appraisal?
A lender-required appraisal is generally absent when there is no mortgage. An independent appraisal or a thorough comparable-sales analysis can still help you assess value, especially for an unusual property.
Is buying a New Orleans condo with cash a good strategy?
It can be, particularly if avoiding mortgage debt fits your finances. Review the association’s budget, insurance, reserves, assessments, maintenance history, and restrictions alongside the unit itself.
Can I buy with cash and obtain financing later?
Potentially, but financing later requires its own approval. Your qualifications, the property’s eligibility, loan timing, and lender requirements will matter. If later financing is essential to your plan, discuss it with a lender before purchasing.
Find the Right Cash-Buyer Opportunity in New Orleans
Raymond Real Estate can help you compare recent sales, evaluate ownership costs, and build an offer around the property and your priorities.
Considering a cash purchase in the French Quarter, Warehouse District, Uptown, or another New Orleans neighborhood? Connect with Raymond Real Estate to explore properties that fit your budget and goals.
Check out this article next