The Condo Seller's Pre-Listing Audit: 8 Things to Check Before You List
Selling a condo in New Orleans is different from selling a single-family home.
You can renovate the kitchen, stage the living room, price the unit correctly, hire professional photography, and generate plenty of buyer interest—and still run into problems because of something involving the condominium association or building.
That is why preparation needs to start before the listing goes live. Many of the same principles in these New Orleans home selling tips apply to condos, but condo sellers also have another layer to address: the financial and physical health of the building itself.
In 2026, that distinction matters more than ever.
Mortgage lenders may look beyond the individual buyer and individual unit to evaluate the condominium project. Insurance, reserves, special assessments, deferred maintenance, litigation, association finances, and other building-level issues can all become part of the transaction.
For New Orleans condo sellers, the takeaway is simple:
Do not wait until you have an accepted offer to discover how your building looks to a buyer's lender.
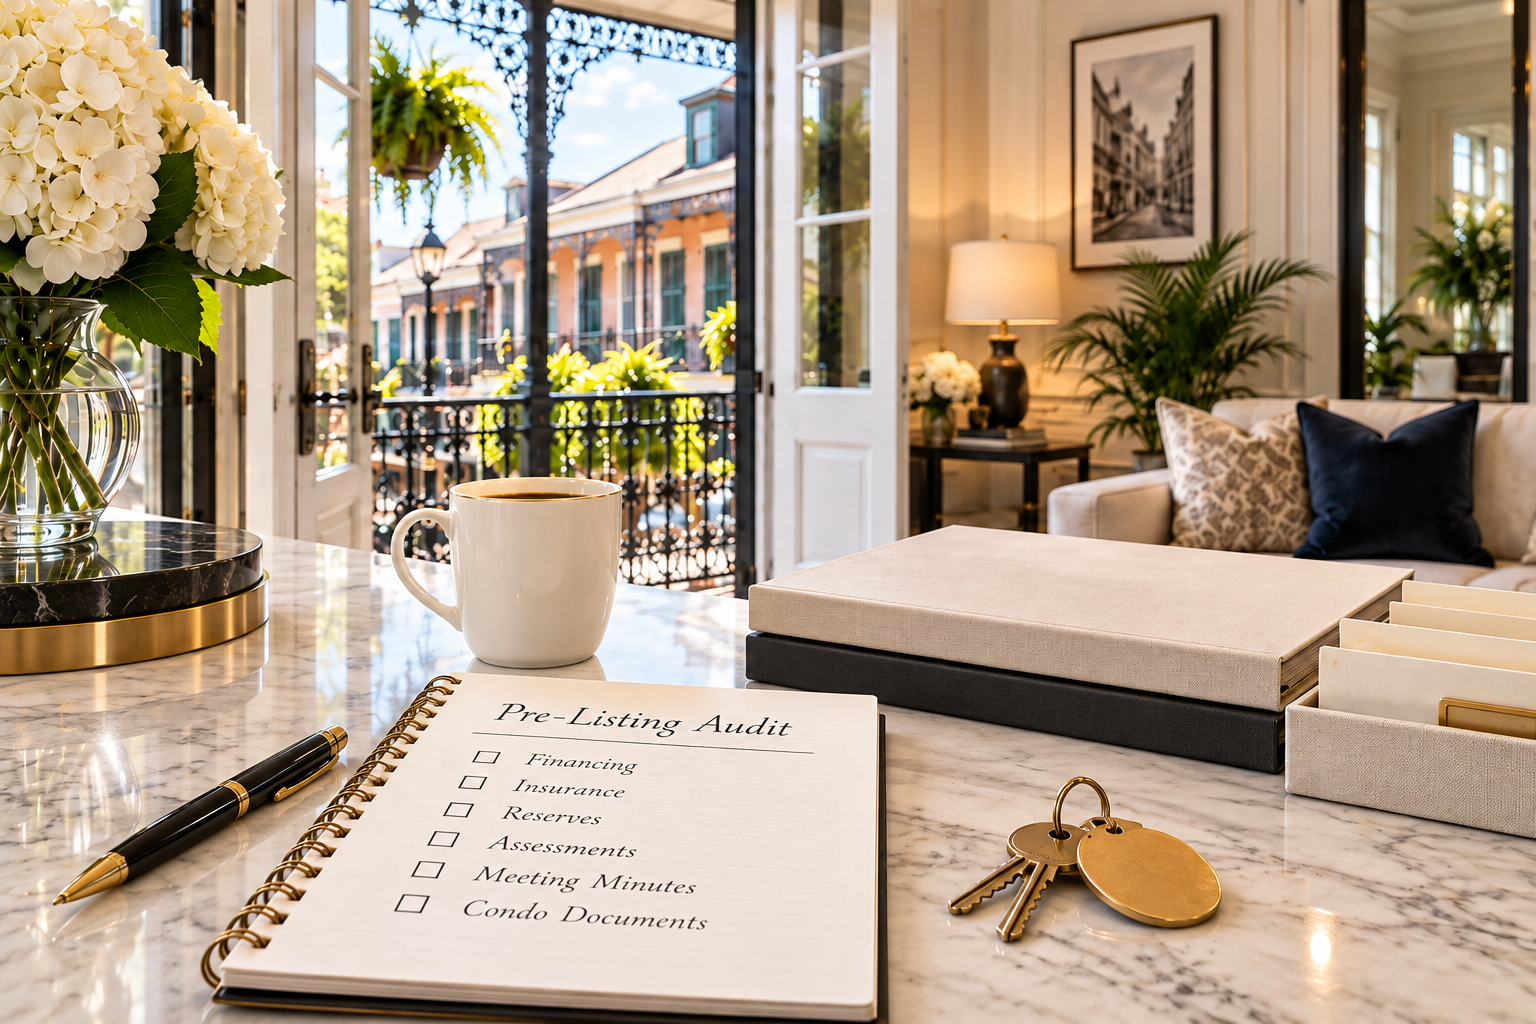
Before putting your condo on the market, conduct a pre-listing audit.
Here are eight things I would want to know before the listing goes live.
1. Find Out Whether Your Condo May Have Financing Issues
One of the most important questions to investigate is whether buyers have historically been able to obtain conventional financing in your condominium project.
A seller may assume:
“My buyer is already preapproved, so financing shouldn't be a problem.”
Unfortunately, condo financing does not always work that way.
A buyer can have excellent credit, strong income, sufficient assets, and a mortgage preapproval—and still encounter a problem because the condominium project does not satisfy the lender's requirements.
Issues involving insurance, reserves, critical repairs, litigation, project characteristics, or other association-level matters can influence the lender's review.
This is often described as the difference between a warrantable and non-warrantable New Orleans condo.
A non-warrantable building is not necessarily a bad building, and a unit in one can still sell. But financing options may be more limited, which can shrink the potential buyer pool.
Before listing, find out what you can about the building's recent financing history.
If several previous transactions have encountered the same lending issue, that is information worth knowing before determining your pricing and marketing strategy.
The goal is not to label the building prematurely.
The goal is to avoid discovering a major financing obstacle three weeks after accepting an offer.
2. Review the Condo Association's Master Insurance
Insurance can become one of the biggest surprises in a New Orleans condo transaction.
The condominium association typically carries a master insurance policy covering portions of the building and common elements.
Before listing, try to understand the basics:
- Who is the carrier?
- When does the policy renew?
- What does it cover?
- What are the deductibles?
- Does the association have wind or named-storm coverage?
- Has the premium increased substantially?
- Are there any known coverage issues?
For condo sellers, being able to document the building's insurance position can help reduce uncertainty. The same concept behind an insurance-ready New Orleans property applies at the condominium level: organized information about coverage, deductibles, maintenance, and building condition can make it easier for buyers and lenders to evaluate the property.
An insurance problem may appear late in the transaction if nobody investigates it early.
That can lead to:
Buyer concern → lender questions → document requests → closing delays → financing problems → potentially a canceled contract.
It is much better to know the situation before the first offer arrives.
3. Know the Association's Reserve Position
Condo reserves are essentially the association's savings for future capital expenses and major repairs.
That might include:
- Roof replacement
- Exterior restoration
- Elevators
- Plumbing systems
- Mechanical equipment
- Waterproofing
- Parking structures
- Balconies
- Other major building components
A reserve account should not be viewed simply as:
“The association has $300,000, so we're fine.”
The important question is whether the amount is reasonable relative to the building's future obligations.
A small association may have relatively modest reserves but also fewer common elements.
A large luxury condominium project may have substantial reserves but also millions of dollars in future capital needs.
This is why buyers are increasingly encouraged to evaluate the entire condo association rather than looking only at the condition of the individual unit.
For sellers, weak reserves can become both a financing issue and a negotiating issue.
A buyer who sees inadequate reserves may immediately start wondering:
“What happens when the next major repair comes?”
Which leads directly to the next part of the audit.
4. Identify Every Existing or Potential Special Assessment
Do not wait for the buyer to discover an assessment.
Before listing, determine whether your association has any:
- Current assessments
- Approved assessments
- Recently completed assessments
- Proposed assessments
- Major projects being discussed that could eventually require additional owner contributions
This distinction matters.
An association might technically have no current special assessment, but the meeting minutes could contain repeated discussions about replacing the roof or repairing balconies.
A sophisticated buyer may interpret that as a potential future financial obligation.
Sellers should understand how special assessments on New Orleans condos work before the property goes on the market.
Imagine your condo is listed for $450,000 and has a $20,000 assessment with payments continuing after closing.
The buyer may ask:
Does the seller pay it?
Does the buyer assume it?
Should the price be reduced?
Can a credit be negotiated?
What exactly is the assessment funding?
There is no reason to begin thinking about those questions after accepting an offer.
Know the numbers ahead of time.
Special assessments do not automatically make a condo difficult to sell. In some cases, an assessment is paying for a valuable building improvement.
The key is being able to explain what it is, how much remains, and what owners are receiving in return.
5. Read the Recent Association Meeting Minutes
This may be one of the most overlooked parts of a condo seller's pre-listing audit.
Read the meeting minutes.
Not just the most recent meeting.
Review several if they are available.
Meeting minutes can reveal issues that do not immediately appear on an association budget.
For example, the board may have discussed:
- Roof leaks
- Plumbing problems
- Elevator repairs
- Masonry deterioration
- Balcony work
- Increasing insurance costs
- Potential litigation
- Delinquent owners
- Reserve concerns
- Security problems
- Major capital projects
None of those items necessarily means the condo cannot be sold.
But you want to know what a buyer might find.
Think about it from the buyer's perspective.
If you had never lived in the building and were considering spending $400,000, $700,000, or $1 million on a unit, you would probably want to know what the board has been discussing too.
Knowing this information early allows you and your real estate agent to prepare for questions instead of reacting to them halfway through the transaction.
6. Check for Deferred Maintenance and Major Building Repairs
Your individual condo may look fantastic.
The building may tell a different story.
Before listing, take an objective look at the common areas and major building components.
Are there obvious signs of:
- Water intrusion
- Damaged stucco
- Deteriorating balconies
- Roof problems
- Broken elevators
- Failing exterior paint
- Drainage issues
- Cracked masonry
- Worn common areas
- Major mechanical work
In an older New Orleans building, some maintenance is inevitable.
Historic buildings require upkeep.
The issue is not whether a building has ever needed repairs.
The important questions are:
What needs to be repaired?
Is there a plan?
How will it be paid for?
This is one reason some New Orleans condos sell quickly while others sit for months. Buyers are increasingly looking beyond the renovated kitchen and paying attention to the building, reserves, insurance, maintenance, financing, and total ownership cost.
Sellers should therefore know whether engineering reports, structural inspections, reserve studies, or major repair proposals exist.
A completed $500,000 exterior renovation may actually become a selling point.
An unidentified $500,000 problem is something very different.
7. Understand the Association's Financial Health and Delinquencies
A condominium association is essentially a small financial ecosystem.
Owners pay dues.
Those dues fund operations, insurance, repairs, management, and reserves.
When too many owners stop paying, the remaining owners and association may experience financial pressure.
Before listing, understand as much as reasonably possible about the association's finances.
Look at the current budget.
Compare income and expenses.
Check reserves.
Determine whether dues recently increased.
Find out whether another increase is expected.
Review any available information regarding owner delinquencies.
One delinquent owner in a 200-unit development may have limited impact.
Several delinquent owners in a six-unit association could be much more significant.
Monthly dues also need context. Sellers should understand what New Orleans condo fees actually cover because buyers are likely to compare both the amount of the fee and the value they receive for it.
And higher dues are not automatically a negative. As explained in Are High Condo Fees Always Bad?, higher fees can sometimes reflect strong insurance, healthy reserve contributions, amenities, staffing, or responsible maintenance.
Strong association finances can help a seller.
If your building has healthy reserves, responsible budgeting, completed capital improvements, and organized management, those facts can help distinguish your condo from competing listings.
8. Gather the Condo Documents Before the Listing Goes Live
This final step can prevent unnecessary delays.
Do not wait until you receive an offer to start searching for every association document.
Gather as much as you reasonably can before listing.
A useful seller file may include:
- Current association budget
- Condo dues
- Insurance information
- Special-assessment details
- Recent meeting minutes
- Rules and regulations
- Condominium declaration
- Bylaws
- Reserve information
- Major repair documentation
- Parking information
- Pet restrictions
- Rental restrictions
- Relevant building contacts
If your unit includes parking or storage, verify exactly how those rights are structured.
Is the parking space:
- Deeded?
- Assigned?
- Limited common element?
- Leased?
- Transferable?
The same applies to storage units, balconies, rooftop rights, and other features that may influence value.
Having organized documentation does two things.
First, it reduces transaction friction.
Second, it communicates that the seller is prepared.
A buyer who receives clear, organized information about the building may feel much more comfortable than a buyer who spends two weeks trying to get basic answers.
Why This Audit Should Happen Before Pricing the Condo
This is where the process becomes especially valuable.
The results of the pre-listing audit can influence your pricing strategy.
Imagine two nearly identical condos.
Both are 1,200 square feet.
Both are beautifully renovated.
Both are in desirable New Orleans locations.
Condo A
The building has strong reserves, appropriate insurance, no known assessment, recently completed exterior work, organized financial statements, and a history of conventional financing.
Condo B
The building has weak reserves, a potential roof assessment, unresolved insurance questions, deferred maintenance, and difficulty obtaining conventional financing.
Those condos should not necessarily be priced as if they are identical.
The condition and financial health of the building influence the marketability of the unit.
Sellers should also look at current New Orleans condo inventory trends before determining an asking price. The number of competing units matters, but so do the quality of those buildings, their monthly costs, financing options, and how directly they compete for the same buyer.
Understanding that before you set the asking price can help prevent months of chasing the market downward.
A Good Pre-Listing Audit Can Also Improve Your Marketing
Not everything uncovered during the audit will be negative.
You may discover excellent selling points.
Perhaps:
- The roof was recently replaced.
- The building completed a major exterior restoration.
- The association has healthy reserves.
- An assessment has already been paid.
- The insurance situation has stabilized.
- The lobby was renovated.
- Elevators were modernized.
- The association recently completed a reserve study.
Those details may not look as exciting in listing photos as a marble kitchen, but sophisticated condo buyers care about them.
A well-run building can be a competitive advantage.
Especially in a market where buyers are scrutinizing association finances more carefully.
Presentation still matters too. Strong real estate listing photos can get buyers to stop on the listing, but the documentation and financial health of the building help give them confidence once they begin serious due diligence.
The best condo marketing combines both:
an attractive unit and a compelling story about the building behind it.
Don't Hide Problems—Prepare for Them
A pre-listing audit is not about finding ways to hide an issue.
It is the opposite.
It is about identifying issues early enough to decide how to handle them.
Maybe the seller pays an assessment before closing.
Maybe the asking price accounts for a renovation project.
Maybe financing options need to be researched.
Maybe documentation from the association can resolve an insurance concern.
Maybe the seller simply needs to be prepared to answer questions.
Problems become much harder to manage when they appear unexpectedly after the buyer has spent money on inspections, appraisal, financing, and due diligence.
Preparation gives everyone more options.
It can also improve the seller's negotiating position. Successful condo sale negotiations often depend on understanding monthly dues, assessments, building finances, insurance, financing, and the buyer's concerns before deciding where there is room to compromise.
Frequently Asked Questions About Selling a Condo in New Orleans
What should I do before listing my New Orleans condo?
Start by reviewing both the individual unit and the condominium association. Gather association financials, insurance information, current dues, assessments, meeting minutes, building repair information, governing documents, and any available information concerning financing eligibility.
Does my condo need to be warrantable to sell?
No. Non-warrantable condos can still be sold, including to cash buyers or buyers using financing designed for non-warrantable projects. However, limited financing options can reduce the size of the potential buyer pool, so sellers should understand the situation before listing.
Can a special assessment make my condo harder to sell?
It can affect buyer interest and negotiations, especially if the assessment is substantial. But an assessment does not automatically make a condo undesirable. Buyers will typically want to know the amount, purpose, payment schedule, and whether additional assessments are anticipated.
Should I pay off a special assessment before selling?
That depends on the amount, the purchase agreement, market conditions, financing, and negotiations between buyer and seller. In some transactions, paying the assessment can make the property easier to market. In others, the parties may negotiate a different arrangement.
Do condo association reserves affect my sale?
Potentially. Buyers and lenders may evaluate the association's reserve funding as part of determining the financial health and financing eligibility of the project. Weak reserves can also make buyers concerned about future assessments.
Can condo insurance affect a buyer's mortgage?
Yes. The association's master insurance can become part of a lender's condominium project review. Insurance issues can create financing complications even when the individual buyer is otherwise fully qualified.
Should I provide condo association documents before receiving an offer?
Having the relevant documentation organized before listing can make the transaction smoother. Exactly when documents are formally delivered depends on the transaction and applicable requirements, but sellers benefit from knowing what information is available before a buyer asks for it.
What is the biggest mistake New Orleans condo sellers make?
One of the biggest mistakes is treating the sale like a single-family home transaction and focusing exclusively on the condition and price of the unit.
With a condo, buyers may effectively evaluate two properties at once: the individual condo and the condominium association behind it.
The Bottom Line
A successful New Orleans condo listing starts before the professional photos are taken.
The unit matters.
The staging matters.
The asking price matters.
But so do the building's insurance, reserves, assessments, finances, maintenance history, governing documents, and financing eligibility.
A condo seller who understands those issues before going to market is in a much stronger position to price the property correctly, answer buyer questions, anticipate lender concerns, negotiate intelligently, and keep an accepted contract moving toward closing.
The goal of a pre-listing audit is not to find a perfect building.
Very few condominium associations are perfect.
The goal is to know what you are selling.
Because in 2026, selling a New Orleans condo successfully means marketing more than the unit.
You are also selling confidence in the building behind it.
This article is for general informational purposes only and is not legal, lending, insurance, tax, or financial advice. Condominium documents, association finances, lender requirements, and individual transactions vary. Sellers should consult appropriate professionals regarding their specific property and transaction.
Check out this article next