Buying a condo in New Orleans has always been a little different from buying a single-family home. In 2026, that difference matters more than ever.
A buyer can have excellent credit, a strong down payment, steady income, and a mortgage preapproval—and still run into financing problems because of the condominium building itself.
That is because lenders do not simply underwrite the person buying the condo. They may also have to evaluate the financial condition, insurance coverage, reserves, ownership structure, maintenance history, and other characteristics of the condominium association.
If you're just beginning your search, our guide on How to Buy a Condo in New Orleans With Confidence explains why evaluating the building and association is just as important as evaluating the individual unit.
And several important condo financing rules changed in 2026.
For buyers considering a condo in the French Quarter, Warehouse District, Central Business District, Uptown, Mid-City, Garden District, or elsewhere in New Orleans, understanding these changes before making an offer can help prevent financing surprises later.
What Changed With Condo Financing in 2026?
Fannie Mae announced a significant series of condominium project-standard changes in March 2026, with additional requirements taking effect throughout the year.
One of the biggest changes took effect for loan applications dated August 3, 2026 or later.
Fannie Mae retired its previous Limited Review process. Established condominium projects that previously qualified for Limited Review generally must now qualify through a Full Review or through an applicable Waiver of Project Review.
That may sound like an obscure mortgage guideline, but it can have very practical consequences for New Orleans condo buyers.
More attention may now be placed on the building's finances and documentation before certain conventional loans can close.
This is also where the distinction between a warrantable and non-warrantable condo becomes important. Our guide to What Makes a New Orleans Condo Warrantable or Non-Warrantable? takes a deeper look at how the building itself can affect financing options.
Your Mortgage Approval Is Only Half of the Equation
One of the most important things condo buyers should understand is this:
You can qualify for the mortgage while the condo project does not.
A lender might approve your:
- income;
- credit;
- debt-to-income ratio;
- employment;
- assets;
- down payment; and
- loan amount.
But financing can still run into trouble if the condominium association does not satisfy the requirements for the mortgage program being used.
This is why asking whether a condo is “financeable” should happen much earlier in the purchasing process.
Condo Reserves Are Becoming Even More Important
One of the biggest issues buyers should watch is the association's reserve funding.
A condominium association generally collects monthly condo fees to operate the property. Part of that money may also be placed into reserves for future major expenses such as:
- roofs;
- elevators;
- exterior repairs;
- plumbing systems;
- mechanical equipment;
- structural repairs;
- common-area improvements; and
- other major capital expenditures.
Fannie Mae strengthened its rules in 2026 for situations in which lenders rely on reserve studies.
For applicable applications dated August 3, 2026 or later, lenders using a qualifying reserve study must verify that the project's budget includes the highest recommended reserve allocation in that study rather than relying on the more aggressive baseline funding approach previously permitted.
There is another major change coming shortly afterward.
For Fannie Mae Full Reviews involving applications dated January 4, 2027 or later, the minimum reserve allocation requirement increases from 10% to 15% of annual budgeted assessment income.
That makes a condominium association's financial planning increasingly important.
Buyers who want to dig deeper into budgets, reserves, meeting minutes, insurance and management should also read our Guide to Evaluating Condo Associations.
Why This Matters in New Orleans
New Orleans contains an unusually diverse condo market.
A buyer could be considering:
- a historic French Quarter conversion;
- a small Uptown condominium association;
- a Warehouse District loft;
- a CBD high-rise;
- a converted historic building;
- a luxury condo tower; or
- a four- or six-unit neighborhood condominium development.
Those buildings can have completely different financial structures.
For example, a smaller condo association may have relatively modest monthly dues but only a handful of owners available to share the expense when the building needs a roof, exterior repair, plumbing work, or another major improvement.
A larger building may collect considerably more in condo fees but also have significant expenses associated with elevators, security, parking garages, pools, common areas, building staff, insurance, and mechanical systems.
The amount of the condo fee by itself therefore tells you very little.
What matters is what the association collects, what it spends, what it has saved, and what major expenses may be coming.
This is why buyers shouldn't automatically avoid a property just because its monthly dues appear high. We explain that distinction in Are High Condo Fees Always Bad? What New Orleans Buyers Should Actually Look At.
Small Condo Associations Received an Important Break
Not every 2026 change makes condo financing harder.
Fannie Mae expanded its Waiver of Project Review rules to include certain new and established condominium projects containing 10 or fewer units.
For projects containing five to ten units, additional requirements apply, including restrictions involving projects that are part of a master association.
This could be particularly relevant in New Orleans, where smaller condominium conversions are relatively common.
A three-unit Uptown conversion and a 150-unit downtown condominium tower may therefore go through very different mortgage-review processes.
Investor Concentration Rules Also Changed
Another potentially positive development involves investor ownership.
Fannie Mae's 2026 changes retired certain previous investor concentration restrictions for established condominium projects undergoing Full Review.
This could help some established New Orleans condo buildings that have significant investor ownership.
However, high investor concentration can still influence other aspects of financing, insurance, marketability, and lender risk.
Buyers should not assume that the removal of one conventional lending restriction means every investor-heavy building will automatically qualify.
Special Assessments Matter
A special assessment is an additional charge imposed on condo owners, usually to fund an expense that regular condo dues or reserves cannot adequately cover.
For example, an association might levy a special assessment for:
- a new roof;
- structural repairs;
- waterproofing;
- elevator modernization;
- exterior restoration;
- major plumbing work;
- insurance-related expenses; or
- hurricane repairs.
A special assessment does not automatically make a condominium impossible to finance.
But lenders may examine what the assessment is for, how much remains outstanding, whether owners are paying it, and whether the underlying work involves significant safety or structural issues.
For a deeper explanation of what buyers should look for, see our guide to Special Assessments on Condos in New Orleans.
That makes the reason behind a special assessment just as important as its dollar amount.
Deferred Maintenance Can Cause Financing Problems
Buyers should also pay close attention to deferred maintenance.
Mortgage agencies are increasingly focused on whether condominium buildings have significant unresolved physical problems.
That means visible building condition is not the only concern.
Buyers should ask about:
- structural inspections;
- engineering reports;
- recurring water intrusion;
- roof condition;
- exterior maintenance;
- elevator issues;
- major upcoming repairs;
- previous insurance claims; and
- unresolved issues discussed during association meetings.
A beautiful renovated condo inside an under-maintained building can still present significant financial and financing risks.
The Condo Association's Financial Statements Matter
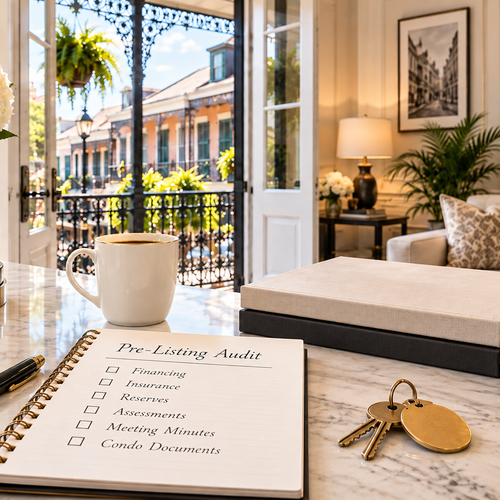
Before buying a New Orleans condo, buyers should try to understand the financial position of the association.
Important documents can include:
- the current annual budget;
- recent financial statements;
- reserve balances;
- reserve studies;
- condo association meeting minutes;
- current and pending special assessments;
- master insurance policies;
- association litigation information;
- delinquency information; and
- condominium declarations and bylaws.
Your lender may request some of these documents independently.
But buyers should review them for their own purposes as well.
Mortgage eligibility asks whether a lender is willing and able to finance the property.
Your own due diligence asks a different question:
Do I want to become one of the owners responsible for this building?
Those are not necessarily the same thing.
Condo Insurance Can Affect Financing Too
Insurance is particularly important when evaluating New Orleans condominiums.
A condo building typically maintains a master insurance policy covering certain portions of the property, while individual owners generally maintain their own unit-level coverage.
Buyers should therefore ask about the association's insurance coverage early in the process rather than waiting until the week before closing.
Questions worth asking include:
What does the master policy cover?
What is the association's deductible?
Has the association experienced significant premium increases?
Has coverage changed recently?
Are there outstanding claims?
Does the lender consider the policy acceptable?
The answers can affect both financing and your long-term ownership costs.
Our guide to What Is an Insurance-Ready Home in New Orleans? also explains why insurance documentation, deductibles and building-level coverage have become increasingly important considerations for local buyers.
FHA Condo Financing Works Differently
Buyers using FHA financing should also understand that FHA condominium requirements are different from conventional financing.
FHA can insure loans in FHA-approved condominium projects, and certain individual units in projects that are not FHA approved may qualify through FHA's Single-Unit Approval process.
To qualify for Single-Unit Approval, the unit generally must be located in a completed project that is not FHA approved and contains at least five dwelling units, along with satisfying other FHA requirements.
So if a condo is not currently listed as FHA approved, that does not necessarily mean FHA financing is impossible.
It does mean the lender should investigate the project's eligibility early.
Buyers considering an FHA loan can also read What Can You Buy With FHA Financing in NOLA? for a broader look at how FHA financing works with New Orleans properties.
Five Questions to Ask Before Making an Offer on a New Orleans Condo
Before becoming emotionally attached to a particular condo, ask these questions:
1. Has anyone recently financed a unit in this building using a conventional mortgage?
A recent financed sale can be useful information, although it does not guarantee that your particular loan will qualify.
2. Does my lender know the exact condominium building I'm considering?
Give your lender the property address and condo association information before you assume the property will work with your loan program.
3. Are there any current or upcoming special assessments?
Find out the amount, purpose, payment schedule, and whether the work has been completed.
4. Does the association have healthy reserves?
Low condo dues are not necessarily a bargain if the association is chronically underfunded.
5. Are there major repairs, litigation, insurance issues, or deferred maintenance?
These can affect both your ownership experience and the building's financing eligibility.
A Cheap Condo Is Not Always the Best Condo Deal
This may become one of the most important lessons for New Orleans condo buyers in the current market.
Imagine two condos are listed for $300,000.
Condo A is in a financially healthy association with good reserves, appropriate insurance, no major deferred maintenance, and straightforward conventional financing.
Condo B has very low monthly fees but minimal reserves, a large upcoming repair project, an insurance issue, and limited financing options.
On paper, both units cost $300,000.
Financially, they can be completely different purchases.
That is why experienced condo buyers evaluate the building along with the unit.
Financing Should Be Investigated Before the Inspection Period Is Almost Over
One of the biggest mistakes a buyer can make is waiting until late in the transaction to investigate condo financing.
Whenever possible, buyers should involve their lender early.
If you are seriously considering a particular building, ask your mortgage professional to begin determining the project's eligibility before too much time and money have been invested into the transaction.
This is especially important when buying in:
- older buildings;
- mixed-use developments;
- investor-heavy buildings;
- buildings with active assessments;
- properties with deferred maintenance;
- newly converted condominium projects; or
- associations with unusual financial or insurance circumstances.
What Does This Mean for New Orleans Condo Buyers in 2026?
The takeaway is not that condo financing has become impossible.
Far from it.
Many New Orleans condos remain perfectly financeable.
The bigger change is that buyers need to understand that the financial health and physical condition of the condominium association increasingly matter to the mortgage process.
In 2026, choosing the right condo means evaluating more than the kitchen, floor plan, balcony, parking space, or view.
You also need to understand the association behind the unit.
Before purchasing a New Orleans condo, review the building's financial condition, reserve funding, insurance, assessments, repairs, and financing eligibility as early as possible.
A little due diligence at the beginning of your search can potentially prevent a major surprise before closing.
Thinking About Buying a Condo in New Orleans?
Every condominium building is different.
A building in the French Quarter may have completely different financing considerations than a Warehouse District high-rise, Uptown conversion, or small Mid-City condo association.
Working with a real estate professional who understands New Orleans condominiums can help you evaluate not only the individual unit but also the building, association documents, financing considerations, and potential resale implications.
Raymond Real Estate can help you search for New Orleans condos and identify important questions to ask before you buy.
Condominium and mortgage guidelines can change, and individual lenders may impose requirements beyond Fannie Mae, Freddie Mac, FHA, or other agency minimums. Buyers should confirm current lending requirements directly with their mortgage professional.
Check out this article next