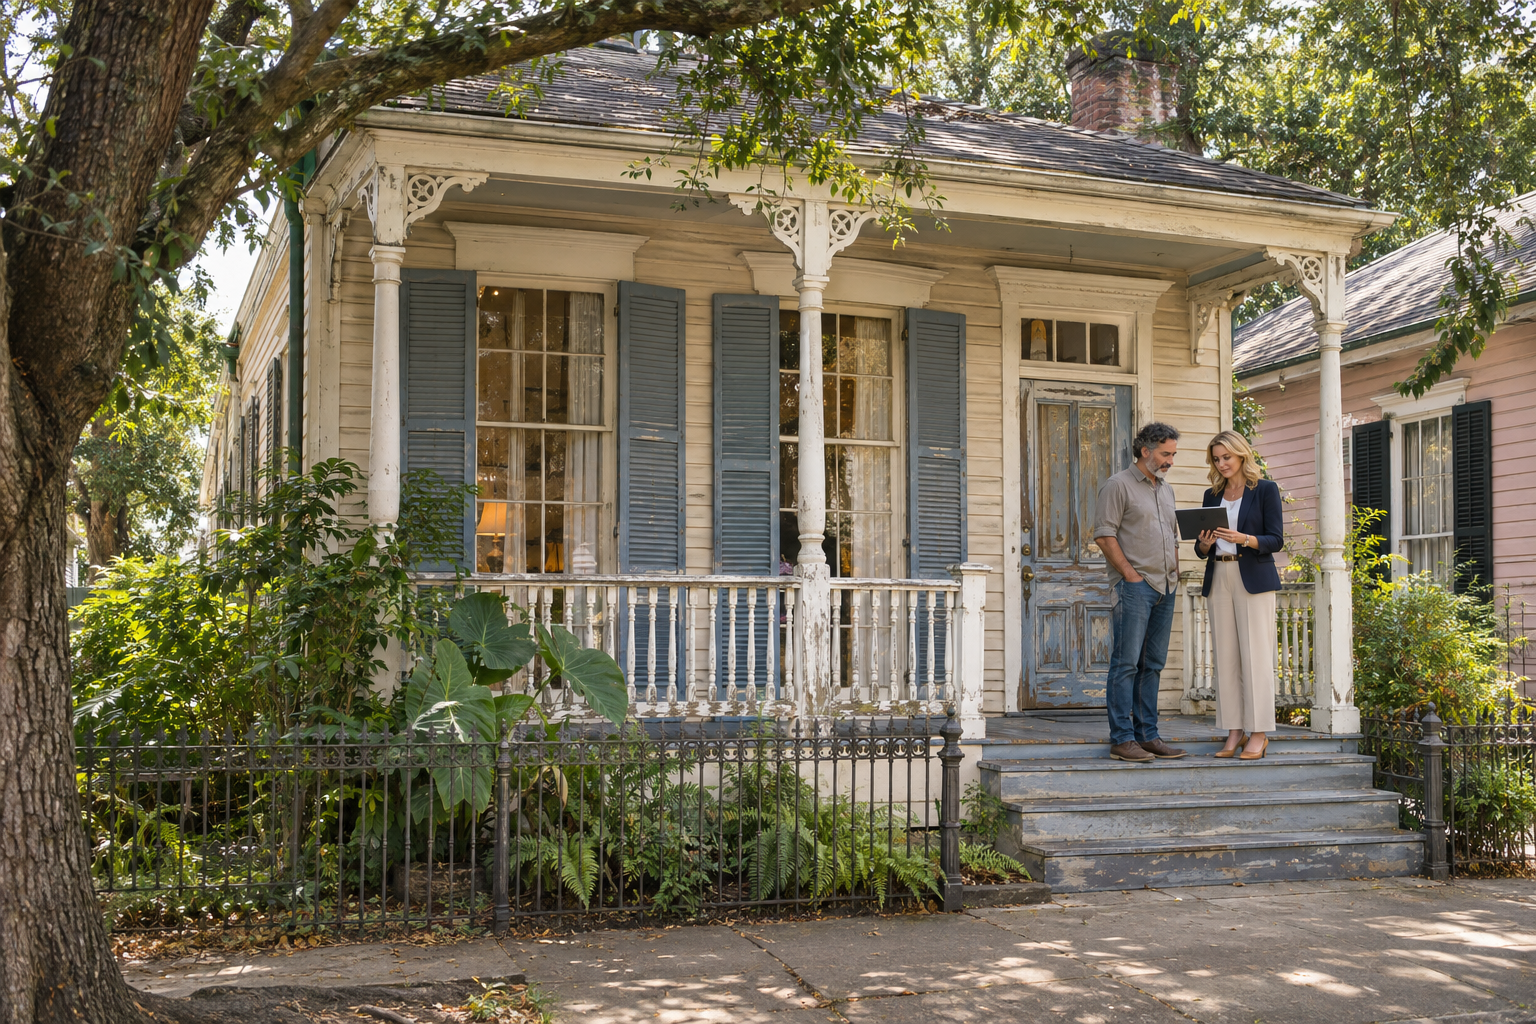
The kitchen could use an update. The roof needs attention. Perhaps you inherited a house, are preparing to relocate, or simply prefer to put your time and money toward your next chapter.
Selling your New Orleans home as-is can be a practical choice. It allows you to explore a sale based on the property’s current condition rather than committing to a major renovation first.
The approach still needs a plan. Your price, disclosures, presentation, and contract terms will shape who considers the property and what you ultimately keep.
Whether you own an Uptown cottage, a Lakeview house, a New Orleans double, or a condominium, start by understanding what you are offering and which buyers can realistically complete the purchase.
What Does Selling a Home As-Is Mean in Louisiana?
In a listing, “as-is” generally communicates that the seller intends to offer the home in its existing condition, with limited or no planned repairs. The signed agreement establishes the actual obligations.
Louisiana also allows parties to exclude or limit the warranty against redhibitory defects, a legal warranty involving certain defects in the property. Louisiana Civil Code Article 2548 requires the limitation to be expressed clearly and specifically brought to the buyer’s attention. Louisiana State Legislature
A description in an advertisement, a warranty provision, and an inspection contingency address different parts of the transaction. Have the closing attorney review the intended warranty language and any questions about its effect.
An as-is strategy can apply to a well-maintained home with dated finishes as well as a property needing significant work. Establish the actual condition before deciding how to position it.
Prepare Your Disclosures Early
Louisiana’s residential property disclosure rules generally require a completed disclosure document, subject to statutory exemptions. Sellers complete it using their own knowledge and belief; the law provides for indicating when information is unknown. An as-is label does not itself create an exemption. Confirm the requirements for your transaction. Louisiana State Legislature
Gather available roof invoices, repair records, permits, inspection reports, warranties, and information about known property concerns. Keep descriptions factual and distinguish documented work from estimates or assumptions.
Louisiana law also addresses liability when a seller knowingly conceals a defect or makes a false claim about the property. A warranty waiver should never be treated as permission to withhold known problems. Louisiana State Legislature
Our guide to seller disclosures in New Orleans explains the information to organize before listing.
Understand Your Likely Buyer Pool
A functional home with an older kitchen presents a different purchase from a house with major structural damage or unusable systems. Both might be advertised as-is, but buyers will evaluate them differently.
Financing eligibility depends on the property, loan program, and lender review. Fannie Mae’s property-condition guidance, for example, distinguishes minor deferred maintenance from deficiencies affecting safety or structural integrity. A seller’s repair preference cannot override the lender’s requirements. selling-guide.fanniemae.com
Ask which issues could affect financing or insurance before narrowing your marketing to a particular type of buyer. A dated interior alone does not establish that the property must be sold for cash.
Our article on an insurance-ready New Orleans home identifies records and questions that can help buyers investigate coverage early.
Price the Property Buyers Will Actually Receive
Begin with comparable sales that reflect your home’s location, condition, layout, parking, outdoor space, and property type. Fully renovated sales can provide context, but they need careful adjustments before being used to price a home requiring work.
A repair estimate is one part of that analysis. Buyers may also account for financing costs, construction time, temporary housing, and uncertainty about work that has not been fully investigated. Investors may include their required return.
There is no universal percentage discount for an as-is home. An arbitrary reduction can leave money on the table or still miss what buyers consider reasonable.
Compare three scenarios: selling in the current condition, making selective improvements, and completing a larger renovation. Our Renovate or Relocate guide can help frame the decision before you commit to a project.
Choose Preparation That Helps Buyers Assess the Home
Even when you plan to sell without major repairs, presentation deserves attention. The aim is to make the property’s condition and useful features easy to evaluate.
Consider a manageable preparation plan:
- Remove unnecessary belongings and clear access to rooms and major systems.
- Clean the home and improve available lighting.
- Trim overgrown landscaping and make entrances accessible.
- Discuss safe showing and inspection access with the appropriate professionals.
- Organize available property records and estimates.
Photographs should accurately show the home’s condition while highlighting features such as original wood floors, a generous porch, a courtyard, or off-street parking.
Before spending on a replacement or remodel, ask whether a smaller action would resolve a meaningful buyer concern. Our guide to pre-listing repairs that pay off provides a starting point for choosing work selectively.
Market the Opportunity With Specific Information
Buyers need enough detail to understand what makes the property worth considering. Pair its strengths with an accurate account of known work.
For example, documented roof replacement and a functioning kitchen awaiting cosmetic updates tell a clearer story than a vague statement that the home “needs TLC.” Identify which improvements are documented, which conditions are known, and which questions remain for the buyer’s investigation.
Market renovation potential carefully. Before suggesting an addition, unit conversion, or major exterior change, investigate whether the proposal is feasible and permitted. Our historic district rules guide explains why the address and scope matter.
Good marketing gives buyers a reason to visit and a useful starting point for their due diligence.
Compare Cash and Financed Offers on Their Actual Terms
A cash offer may remove the mortgage approval process, but the contract may still contain inspection rights, other contingencies, or an assignment provision. Request evidence of funds and review the proposed terms before treating the offer as certain.
A financed offer deserves the same careful review. Consider the buyer’s lender status, the property’s likely eligibility, appraisal provisions, requested credits, and schedule.
For either offer, evaluate the deposit, review periods, closing date, seller obligations, and what happens if a condition is not satisfied. Our article on cash offers versus financed offers explains why the funding label is only one part of the comparison.
Look at Expected Proceeds Alongside Timing
A higher offer can produce a different result once credits and expenses are included. Compare the numbers using the same categories.
The example below uses entirely invented figures. It is not a New Orleans market estimate, a statement of typical fees, or a prediction about either type of buyer.
| Illustrative item | Cash offer | Financed offer |
|---|---|---|
| Purchase price | $240,000 | $255,000 |
| Agreed buyer credit | $0 | −$8,000 |
| Assumed seller closing charges, including negotiated brokerage compensation | −$17,000 | −$18,000 |
| Assumed mortgage payoff | −$140,000 | −$140,000 |
| Estimated closing proceeds | $83,000 | $89,000 |
| Additional ownership expenses while waiting to close, paid outside closing | −$1,000 | −$3,500 |
| Proceeds less those additional ownership expenses | $82,000 | $85,500 |
In this illustration, the financed offer leaves $3,500 more after the listed expenses. The seller must still weigh the conditions and likelihood of each transaction closing. Different assumptions could change the result.
Use actual quotes, payoff estimates, negotiated compensation, credits, and timelines for your property. Avoid counting an expense both at closing and again outside closing.
Our guide to how much New Orleans sellers could walk away with explains how a seller net sheet supports that comparison.
Plan for Inspections and Repair Discussions
Discuss inspection access, deadlines, and the seller’s intended repair position before signing. Louisiana’s disclosure statute preserves inspection rights; the purchase agreement governs the specific review process and available contractual options. Louisiana State Legislature
If a buyer requests repairs or a credit, evaluate the request under the signed terms. Whether to accept a change is a negotiation; the ability to terminate or enforce an existing obligation requires a separate contract review.
A credit also may not resolve a lender-required physical repair. Have the lender confirm what the transaction needs before assuming a price adjustment will allow it to close. selling-guide.fanniemae.com
Our guide to buyer contingency clauses in New Orleans offers additional context for the provisions worth reviewing.
Build Your As-Is Selling Strategy Before Accepting an Offer
Start with a realistic assessment of the home, its likely buyers, and the preparation you are willing to undertake. Then compare your pricing options and expected proceeds before committing to a sale.
Raymond Real Estate helps New Orleans homeowners evaluate condition, pricing, marketing, and offers together. Whether you prefer to sell in the current condition or make a few targeted improvements first, the plan should reflect your property and your priorities.
Thinking about selling your New Orleans home as-is? Request a home value estimate or contact Raymond Real Estate to compare your options.
Frequently Asked Questions About Selling a New Orleans Home As-Is
Can I sell my home without making repairs?
It may be possible when a buyer accepts the condition and the transaction can satisfy its other requirements. Price the actual property, disclose appropriately, and review proposed repair obligations before signing.
Does an as-is sale automatically mean cash only?
No. Financing depends on the home’s actual condition and the loan program’s requirements. Have a lender evaluate specific concerns rather than deciding eligibility from the listing description alone.
Can a buyer still inspect an as-is home?
An as-is description does not automatically remove inspections. Review the purchase agreement’s access provisions, deadlines, contingencies, and remedies with your agent and, where needed, your attorney.
Do I need a disclosure if I have never lived in the property?
Lack of occupancy alone does not determine whether a statutory exemption applies. Confirm your obligations for the particular transfer and complete any required disclosure using what you actually know.
How much less should I expect when selling as-is?
There is no fixed discount. Location, condition, comparable sales, repair scope, buyer financing, and the terms of the offer all affect the outcome. Compare realistic scenarios for your property.
Check out this article next