A strong offer can lose momentum quickly if the deposit is late. So, when is earnest money due? In most home purchases, it is due shortly after the seller accepts your offer, on the deadline written into the purchase agreement. In New Orleans, where contracts, contingencies, and property conditions can carry real complexity, that deadline deserves the same attention as the purchase price.
Earnest money is more than a good-faith gesture. It is a contractual obligation that shows a buyer is prepared to proceed under the terms of the agreement. Knowing when to deliver it, where it should be held, and what may happen if the transaction changes can help you move forward with confidence.
What earnest money does in a real estate transaction
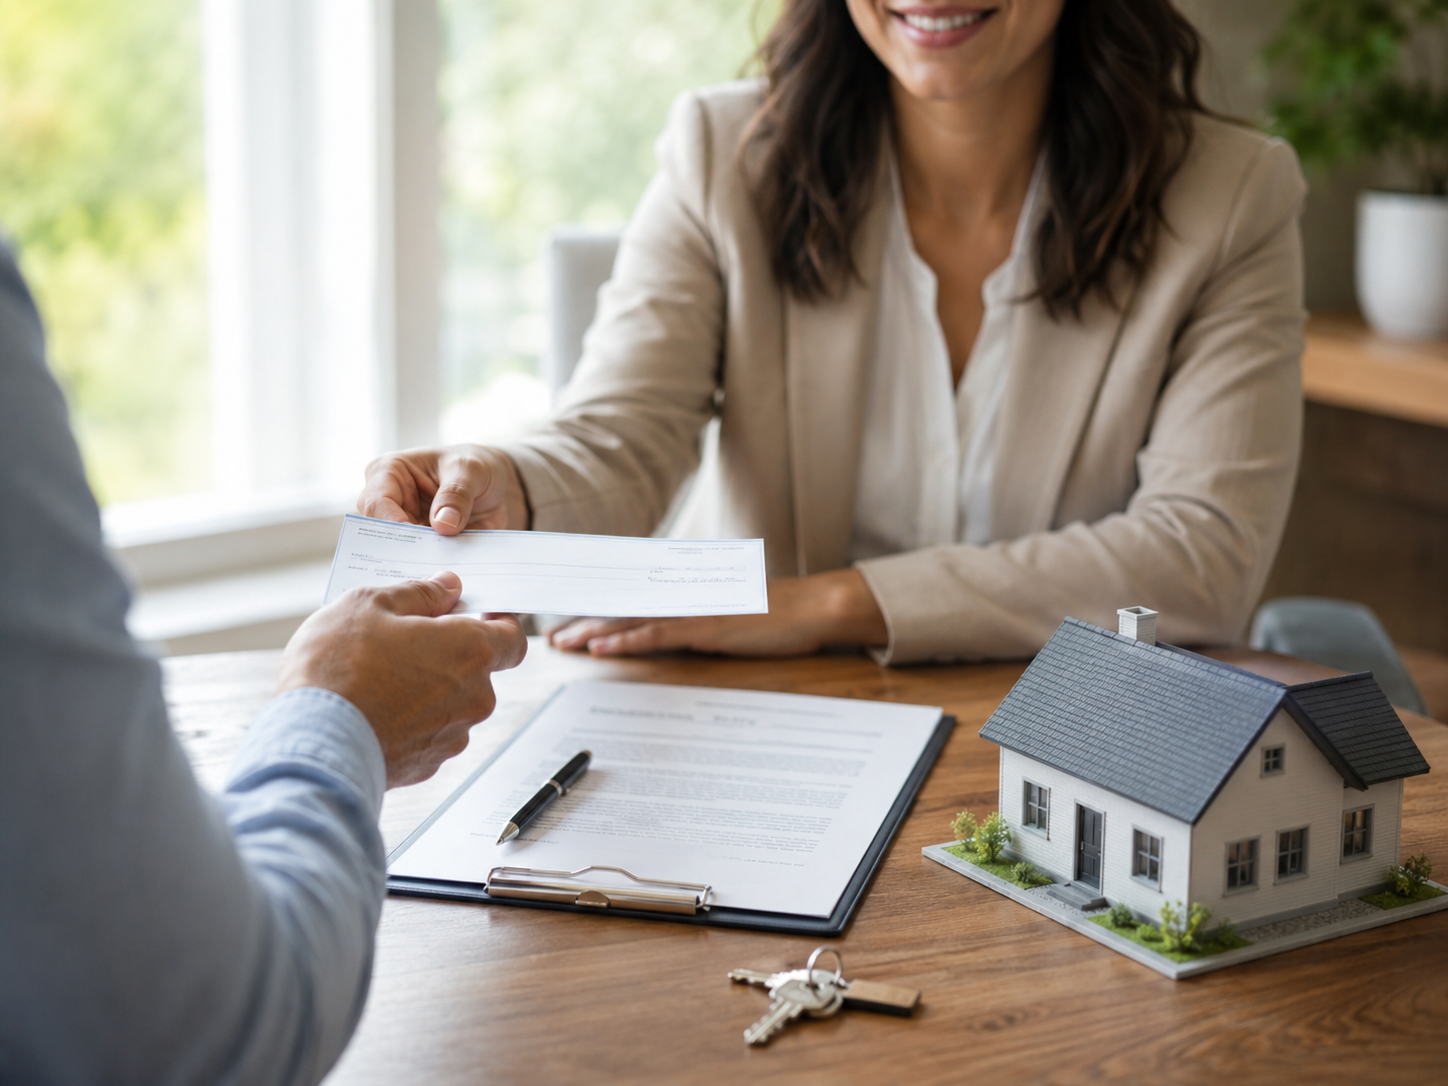
Earnest money is a deposit a buyer provides after reaching an agreement with the seller. The funds are generally held in escrow by a title company, brokerage, or other authorized party until closing or until the contract directs their release.
At closing, the deposit is typically applied toward the buyer's cash to close, which can include the down payment, closing costs, and prepaid expenses. It is not an extra fee on top of the purchase price. Instead, it is part of the buyer's financial commitment to the transaction.
The amount varies with the property, price point, level of competition, and negotiated terms. A buyer pursuing a condominium in the Warehouse District may approach the deposit differently than a buyer competing for a historic Uptown home with multiple offers. A larger deposit can make an offer feel more compelling, but it also means more money is at stake if you fail to meet the contract's requirements.
When is earnest money due after an offer is accepted?
The purchase agreement controls. There is no universal nationwide rule that says earnest money must be delivered within a certain number of days. Many contracts call for delivery within a few business days of acceptance, but the exact deadline may be one, two, three, or more days depending on what the parties negotiated and which contract form they use.
Read the language carefully. The clock may begin when all parties have signed, when the buyer receives notice of acceptance, or on the next business day. A deadline that falls on a weekend or legal holiday may be treated differently under the agreement. These details can seem minor until a wire transfer, bank hold, travel schedule, or missing signature puts the buyer at risk of being late.
For Louisiana buyers, the safest approach is simple: arrange the funds before making an offer and send the deposit as soon as the agreement is fully executed. Do not wait until the final day simply because the contract permits it. Early delivery demonstrates reliability and leaves room to resolve an administrative issue without creating unnecessary tension.
Who receives the deposit?
Your signed agreement should identify the escrow holder and provide delivery instructions. In many transactions, a title company holds the earnest money in escrow. In others, a brokerage may hold it in a trust account, subject to applicable rules and the terms of the contract.
Never send funds based solely on an emailed change in wiring instructions. Wire fraud is a serious risk in real estate transactions, particularly when large deposits are involved. Confirm instructions by calling a known phone number for the title company or escrow holder, not a number included in a suspicious email. Before sending a wire, verify the recipient name, account details, and amount verbally.
A cashier's check may also be acceptable, depending on the escrow holder's procedures. Your agent can help coordinate the process, but the buyer remains responsible for ensuring the deposit arrives on time and obtaining confirmation that it was received.
What happens if earnest money is late?
A late earnest-money deposit can be treated as a breach of the purchase agreement. The seller may have rights under the contract to demand performance, extend the deadline, cancel the agreement, or pursue other remedies. What happens in practice depends on the language of the agreement, the timing, and whether the seller has already taken action.
If you realize you may miss the deadline, communicate immediately. Your agent should notify the listing side and work to document any agreed extension in writing. A verbal assurance that the seller is "fine with it" is not enough when a signed contract says otherwise.
In a competitive situation, lateness can also affect the working relationship between buyer and seller. Even if the seller allows a short extension, it may raise concern about the buyer's ability to meet later milestones, such as inspection decisions, loan approval, or closing. Prompt action protects both your contractual position and the credibility of your offer.
Is earnest money refundable in Louisiana?
It can be, but it is not automatically refundable in every circumstance. The answer depends on the contract terms and the reason the transaction does not close. This is where contingencies matter.
A well-written purchase agreement may allow a buyer to recover the deposit if they terminate within the required timeline due to an unsatisfactory inspection, inability to obtain financing under the agreed conditions, a low appraisal, title issues, or another contractually protected contingency. The buyer must follow the notice requirements precisely. Missing an inspection deadline or failing to provide required documentation can weaken protections that otherwise appeared straightforward.
For example, an inspection may reveal significant foundation concerns, roof issues, plumbing defects, or insurance challenges. These risks can be especially relevant with New Orleans' older housing stock and distinctive historic properties. If the contract gives the buyer an inspection period and the buyer timely exercises the right to cancel or renegotiate under that provision, the deposit may be returned according to the agreement.
The opposite is also true. If a buyer simply changes their mind after contingency periods expire, cannot perform for a reason not covered by the contract, or defaults without a protected basis, the seller may seek to retain the earnest money. Whether that is the final remedy depends on the agreement and the facts of the transaction. When a dispute arises, the escrow holder may require a written release from both parties or follow applicable legal procedures before disbursing funds.
How much earnest money should you offer?
There is no single ideal number. The right deposit should be meaningful enough to support a serious offer while remaining proportionate to your comfort level and the protections in the contract. Market conditions matter. A highly desirable home with competing offers may call for a stronger deposit than a property that has been available for several weeks.
Buyers should evaluate the entire offer, not just the earnest-money amount. Price, financing strength, inspection terms, appraisal provisions, closing timeline, and seller preferences all influence how an offer is received. Offering more earnest money can be persuasive, but waiving protections or increasing the deposit without understanding your exposure can create avoidable risk.
A thoughtful strategy is particularly valuable for condominiums. In addition to inspecting the unit, buyers may need time to review association documents, budgets, rules, insurance information, pending assessments, and other factors that affect ownership. The deposit should align with a contract timeline that gives you a reasonable opportunity to complete that due diligence.
A practical checklist before sending funds
Before delivering earnest money, confirm four essentials: the exact amount, the deadline, the authorized escrow holder, and the approved delivery method. Keep a copy of the fully executed purchase agreement and save your receipt, wire confirmation, or proof of delivery.
You should also understand the contingency dates that follow. Earnest money is only one early obligation. Inspection periods, financing deadlines, appraisal requirements, title review, and closing preparations each require timely decisions. A carefully managed calendar is one of the most effective ways to preserve your rights throughout the purchase.
At Raymond Real Estate, buyers receive guidance that accounts for the contract details as well as the realities of the New Orleans market. Whether you are purchasing your first condominium or making a strategic move into a historic home, the goal is not merely to meet a deadline. It is to make each commitment with a clear understanding of what it means.
If you are preparing to write an offer, have your earnest money accessible, verify the delivery process before acceptance, and give every contract deadline the attention it deserves. That level of preparation helps turn an accepted offer into a well-managed path to closing. Learn More
Frequently Asked Questions About When Earnest Money Is Due for a Home Purchase
When is earnest money due after making an offer on a home?
Earnest money is typically due shortly after the buyer and seller sign the purchase agreement. The exact deadline is stated in the contract and may be within a few days of acceptance. Buyers should review the agreement carefully because missing the deadline could create a contractual issue.
What is earnest money?
Earnest money is a deposit a buyer provides to demonstrate that they are serious about purchasing the property. The money is generally held by a designated escrow holder until the transaction closes or is otherwise resolved according to the purchase agreement.
Do I pay earnest money when I submit the offer?
Not necessarily. In many transactions, the buyer agrees to an earnest money amount in the offer but does not actually deliver the funds until after the seller accepts the contract. The purchase agreement will specify when and where the deposit must be delivered.
How much earnest money is required when buying a home?
There is no universal amount. The deposit may be a flat dollar amount or an amount negotiated between the buyer and seller. Market conditions, the purchase price, and the competitiveness of the offer can all influence how much earnest money a buyer chooses to offer.
Where does the earnest money go?
Earnest money is normally deposited into an escrow account with the party identified in the purchase agreement, such as a title company, closing attorney, brokerage, or other authorized escrow holder. It is not typically paid directly to the seller.
Does earnest money go toward the purchase price?
Yes. If the transaction closes successfully, the earnest money is generally credited toward the buyer's funds due at closing, such as the down payment or closing costs.
Can I lose my earnest money if I back out of the purchase?
Possibly. Whether the buyer receives the deposit back depends on the terms of the purchase agreement and the reason the transaction is terminated. Inspection, financing, appraisal, or other contingencies may provide a buyer with the right to terminate under certain circumstances.
Is earnest money refundable if the home inspection finds problems?
It can be, depending on the inspection provisions of the contract. If the buyer properly exercises an inspection or due-diligence right within the required timeframe, the purchase agreement will determine what happens to the earnest money.
What happens if I miss the earnest money deadline?
Missing the deadline can potentially place the buyer in breach of the purchase agreement or give the seller certain contractual remedies. Buyers should arrange for the deposit promptly and confirm that the escrow holder has received it.
Should I wait until the earnest money deadline to send it?
Usually, no. Once the purchase agreement is accepted, it is generally a good idea to arrange the deposit as soon as possible rather than waiting until the final day. Your real estate agent or closing professional can confirm the amount, deadline, and proper method of delivery.
How do I know exactly when my earnest money is due?
Check the signed purchase agreement. It should identify the earnest money amount, the party responsible for holding it, and the deadline for delivery. Because contract requirements vary by transaction and location, the signed agreement should always control the timeline.
Check out this article next